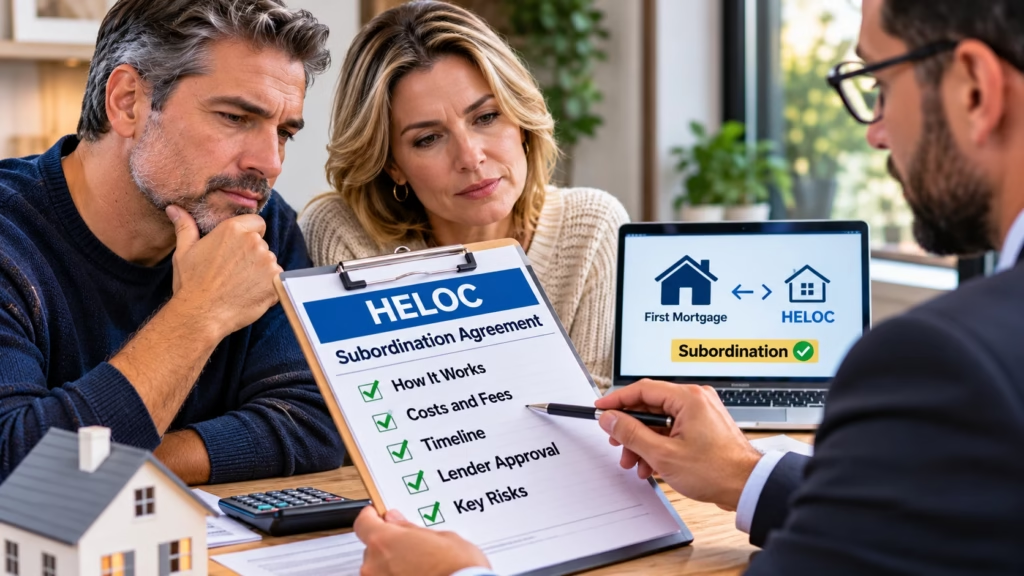
A HELOC subordination agreement can determine whether your first-mortgage refinance closes on schedule. Keeping an existing home equity line of credit often requires the HELOC creditor to agree that its lien stays behind the replacement first mortgage. This guide explains the process, costs, scheduling risks, and alternatives, using federal consumer guidance and Fannie Mae underwriting rules. Actual fees and deadlines depend on your lender, transaction, and state law.
Table of Contents
What subordination means
A home equity line of credit usually records a second lien behind the purchase mortgage. When the owner refinances the first mortgage, the old first lien is released. The HELOC lien could then have priority over the replacement loan under applicable law. A subordination agreement is the HELOC creditor’s written consent to remain junior. It does not forgive the HELOC balance, eliminate the lien, or automatically change its interest rate.
Fannie Mae generally requires execution and recordation of a resubordination agreement when a second lien remains during a refinance, subject to specified state-law exceptions. See its Selling Guide. A zero outstanding balance does not mean an open line is released.
Why lien priority matters
Lien priority determines which secured creditor is paid first from collateral proceeds under applicable law. The refinance lender normally expects a first-priority mortgage. The title company checks recorded mortgages, judgments, and releases before confirming that the new mortgage can occupy that position.
State recording laws and equitable subrogation can affect the result. They are not a substitute for obtaining the documents required by the investor and closing agent. The agreement must identify the right property and loans and be executed by the party authorized to bind the HELOC creditor.
When lenders require resubordination
The need commonly arises when an owner refinances a first mortgage while retaining a HELOC or other second mortgage. The new lender reviews the existing junior financing, its repayment terms, and its priority. A transaction that pays off a non-purchase-money second may be classified differently for underwriting than one that leaves it outstanding.
Fannie Mae distinguishes limited cash-out and cash-out refinances based partly on subordinate debt payoff and cash received. Do not assume paying off the HELOC simplifies every aspect of approval. Ask the new lender how each alternative affects loan classification, pricing, and eligibility.
Can a HELOC lender refuse approval?
Yes. The Consumer Financial Protection Bureau explains that HELOC creditors may refuse permission for a first-mortgage refinance. The decision can reflect property value, credit quality, the proposed new mortgage amount, the unused HELOC commitment, and internal collateral policy.
If the creditor declines, ask for the reason in writing and whether a smaller first loan, reduced HELOC limit, partial paydown, or new appraisal would permit reconsideration. Payoff and closure are other possibilities, but can sacrifice future access to credit and change the refinancing economics.
Documents you should gather
Start with the HELOC agreement, current statement, credit limit, balance, maturity date, account identifier, and creditor contact. Ask the new lender for the proposed loan amount and relevant disclosures. Obtain the title report and property valuation or appraisal required by the HELOC creditor.
Check whether the HELOC has changed owners or servicers. A customer-service representative may receive a request without authority to execute the agreement. Ask which department handles subordinations, what secure submission method is accepted, and whether the closing agent must submit the package.
The application process step by step
Disclose every recorded mortgage and line of credit to the refinance lender. Request the HELOC creditor’s current checklist before paying nonrefundable fees. Send the completed package with all required signatures, loan estimates, title information, and valuation. Obtain a reference number and written acknowledgment that the file is complete.
Respond promptly to conditions, including requests to lower the credit line. Have the settlement agent review the executed instrument and arrange recording where required. Finally, confirm that the refinance lender accepts the recorded priority. An initial verbal approval is not the same as a completed subordination.
How long it takes
No single federal deadline governs a HELOC creditor’s voluntary subordination review. Timing varies with the lender, documentation, appraisal, title defects, and county recording. Routine applications may move within weeks, while complicated transactions can take longer.
A two-to-six-week buffer is a planning illustration, not a guaranteed processing standard. Obtain the lender’s own estimate and begin early. Monitor your rate-lock expiration because an otherwise small delay can require extension charges or repricing.
Fees and closing charges
Potential expenses include a HELOC review fee, document preparation, appraisal or valuation, title examination, recording, and settlement administration. A late closing can add a rate-lock extension. These are possible categories, not mandatory charges or nationally standardized amounts.
Request a written itemization and clarify which fees are refundable after denial. Compare the refinance Closing Disclosure with the latest Loan Estimate. Fees paid directly to the HELOC creditor should still be included in your own total-cost calculation.
Hypothetical fee calculation
Assume a $250 lender review fee, $90 recording charge, and $160 incremental settlement charge. Direct subordination costs total $500. If a delay adds a hypothetical $450 rate-lock extension, the combined extra cost becomes $950. These amounts are examples, not actual lender quotes or market averages.
If refinancing reduces monthly payments by $125 and total incremental closing costs are $3,500, simple cash-flow break-even is 28 months. That calculation ignores differences in principal, term, taxes, and amortization. Our mortgage recast versus refinance guide explains why payment savings alone can mislead.
Combined loan-to-value requirements
Combined loan-to-value, or CLTV, compares secured financing exposure with the appraised home value. A HELOC creditor may consider the entire authorized credit line rather than just the drawn balance, depending on its policy and the loan program.
Consider a $400,000 property, a proposed $280,000 first mortgage, and a $60,000 HELOC limit. Combined potential exposure is $340,000, or 85% of value. If only $10,000 is drawn, the outstanding debt is smaller, but the creditor may still evaluate unused borrowing capacity. Confirm the exact underwriting formula.
A zero-balance HELOC is still a lien
Paying a HELOC balance to zero does not necessarily terminate the credit agreement or release the recorded security instrument. An open line can permit future advances and therefore still concern the refinance lender. A formal subordination or payoff-and-release process may remain necessary.
Ask the creditor whether a credit-line reduction or closure is required. If closing, request written instructions, check for early termination fees, and verify that the lien release is recorded. Do not treat an online statement showing $0 as evidence of a cleared title.
Can the HELOC terms change?
Subordination concerns lien priority, but a creditor may impose conditions such as freezing future advances, reducing the limit, or changing specific contractual provisions. A variable-rate HELOC can continue to change under its existing index and margin even after the first mortgage is refinanced.
Read every amendment carefully. Confirm whether the draw period, repayment period, maturity, payment method, or available credit changes. Ask for an explanation of any new fee or covenant before agreeing. If conditions are unfavorable, compare paying off the line or revising the refinance amount.
Subordination versus HELOC payoff
With subordination, the existing HELOC stays in place behind the replacement first mortgage. With payoff, the HELOC debt is extinguished and the lien should be released after the required process. Keeping it may preserve liquidity; paying it off can simplify title but consume cash or increase first-mortgage borrowing.
The better choice depends on rates, terms, closing costs, loan-to-value, and expected time in the home. Consolidating HELOC debt into a longer mortgage can reduce the payment while increasing total interest. Model the balances separately and together rather than relying on the headline rate.
If the request is denied
Ask whether denial reflects valuation, credit policy, documentation, an unacceptable first-mortgage amount, or a title defect. Request the reconsideration process and identify whether a partial paydown or lower credit limit could help. If the issue is an error in the recorded documents, involve the title company or real estate attorney.
A different refinance lender may have different underwriting requirements, but cannot disregard lien priority. Never conceal the HELOC. A written closing strategy is preferable to rushing into payoff, particularly if that would reduce emergency reserves.
Rate-lock and scheduling risks
A refinance rate lock has an expiration date. If subordination takes longer than expected, the borrower may face a lock extension, repricing, or postponed closing. Ask the loan officer who tracks the request and when the completed agreement must arrive.
Maintain a timeline of package submission, document acceptance, valuation, approval, signature, and recording. Confirm changes in writing. Do not repeatedly submit conflicting versions of the loan amount or credit limit without explaining the revision.
Closing Disclosure timing
For most covered closed-end mortgage refinances, the lender must provide a Closing Disclosure at least three business days before consummation. A HELOC itself generally uses different Truth-in-Lending disclosures. The two disclosure regimes should not be confused.
Review the CFPB guidance and compare final fees with your Loan Estimate. Certain material corrections restart the waiting period, but not every fee adjustment does. Ask the settlement agent how a late subordination fee will be disclosed.
The separate rescission right
Some refinances of a principal residence have a federal three-business-day right of rescission after the required events occur. This is separate from receiving the Closing Disclosure before closing. Exceptions and special rules apply, including certain transactions with the existing creditor.
See the CFPB explanation. Follow your actual cancellation notice and seek legal advice about unusual situations instead of assuming all refinances can be canceled on the same schedule.
Title insurance and recording
A title company reviews lien documents, recording information, judgments, and other encumbrances. The subordination instrument must correctly identify the property, HELOC lien, and new first mortgage. A signed agreement that is not recorded as required may be insufficient.
Fannie Mae specifically warns that title insurance against an improperly resubordinated lien does not excuse compliance with its rules. Ask for the recording reference and retain the final title policy and executed agreement with your closing records.
Special cases and transferred HELOCs
A HELOC may be serviced by a different institution from the creditor with authority to execute a subordination. Shared-appreciation contracts, deferred assistance loans, and other recorded interests can have requirements that differ from ordinary second mortgages.
Disclose every secured interest, even if it is marketed as a grant or deferred-payment program. Some programs impose occupancy, resale, or repayment conditions. Verify the authorized signing party and obtain professional advice when title ownership or priority is disputed.
Comparing true refinance savings
Evaluate monthly principal and interest, total remaining interest, loan term, closing expenses, HELOC costs, escrow, and whether principal increases. Restarting a thirty-year term may lower the payment without reducing total cost. Include the expected time you will retain the loan.
Use a consistent amortization comparison. Meridian Pioneer’s mortgage points versus lender credits guide explains upfront pricing choices, and our refinance guide discusses break-even analysis.
Questions for both lenders
Ask the HELOC creditor: Is subordination available? What are the document requirements and fees? Are charges refundable if denied? Does CLTV use the full credit limit? Must draws be frozen? Who signs, and what is the current processing estimate?
Ask the first-mortgage lender: Is subordination mandatory for this program? What is the document deadline? Who records the agreement? What if the rate lock expires? Would HELOC payoff change the refinance classification? Request written answers.
Avoidable mistakes
Common errors include waiting until the final week, assuming a zero balance releases the lien, failing to disclose a second mortgage, ignoring unused HELOC capacity, and relying on verbal approval. Comparing only monthly payments can also hide meaningful costs.
Keep a file containing both lenders’ instructions, title report, valuation, loan estimates, HELOC statements, fee receipts, and rate-lock details. Verify names, addresses, balances, and account numbers on every document before submission.
Frequently asked questions
Can I refinance with an open HELOC? Often, if the first lender accepts it and lien priority is resolved. Can the HELOC lender refuse? Yes. Must I pay it to zero? Not always. Is there a standard fee? No; request a lender-specific quote. How long does approval take? It varies; plan ahead.
Does subordination refinance the HELOC? No. Does it change the HELOC rate? Not inherently, although separate amendments can. Is a paid-off HELOC automatically removed from title? No; verify the recorded release. If the agreement is denied, discuss restructuring or payoff before your rate lock expires.
Sources and editorial notes
Primary sources: Fannie Mae Selling Guide B2-1.2-04, Fannie Mae subordinate financing definitions, CFPB HELOC refinance guidance, and CFPB closing checklist. Verify current lender and state rules before taking action.
Meridian Pioneer editorial team. We produce independent consumer-finance explainers grounded in primary sources and clearly identified hypothetical calculations. This article is educational, not individualized legal or lending advice. Consult a qualified mortgage professional or real estate attorney for transaction-specific questions.