No Money Down Semi Truck Financing in Texas with best rates, may qualify for fast approval & high approval programs. Compare top lenders for 2026.
Start Driving Without Draining Your Capital
Breaking into the Texas freight market has never required more strategic capital management. Equipment prices remain high, insurance premiums have increased, and operating reserves are critical during the first 90 days. That’s why No Money Down Semi Truck Financing in Texas has become one of the most searched high-CPC commercial lending topics in 2026.
For owner-operators and small fleet builders, zero down financing offers a way to preserve liquidity while securing revenue-generating equipment immediately.
This guide explains:
- How zero down commercial truck loans work
- Who qualifies (including bad credit applicants)
- Where to find best rates and may qualify for fast approval
- Current interest rate ranges in Texas
- Practical strategies for high approval odds
If you want to maximize cash flow and secure same day funding options from top lenders, this article is built for you.
What Is No Money Down Semi Truck Financing?
No money down financing means the lender funds 100% of the truck’s purchase price. Instead of putting 10–25% upfront, the entire cost is financed through structured monthly payments.
In commercial trucking, this is typically structured as:
- Equipment financing agreement
- Commercial vehicle loan
- Lease-to-own (less common but available)
Because the lender assumes greater risk, underwriting is more detailed. However, Texas remains one of the most competitive states for commercial truck funding due to its freight volume and transportation infrastructure.
How Zero Down Financing Works in Texas
Zero down semi truck loans rely on risk-based underwriting. Instead of focusing only on credit score, lenders evaluate the complete borrower profile:
Core Underwriting Factors
- Personal credit score
- Time in business
- CDL experience
- Revenue projections
- Bank statement strength
- Truck year and mileage
Applicants with strong operational indicators can often offset mid-tier credit.
Approval Timeline
- Online application: 5–15 minutes
- Soft credit pre-qualification: minutes
- Conditional approval: same day
- Final underwriting: 24–48 hours
- Funding: 1–3 business days
Many online lenders now offer may qualify for fast approval pre-screens, especially for applicants with complete documentation.
Key Benefits of Zero Down Semi Truck Loans
1. Preserve Working Capital
Keeping $15,000–$30,000 in reserve allows you to cover:
- Insurance down payments
- IRP and registration
- Fuel advances
- Initial maintenance
Liquidity during the first 60–90 days dramatically increases survival rates for new owner-operators.
2. Faster Market Entry
Zero down structures eliminate delays caused by capital accumulation.
3. High Approval Options
Specialized commercial lenders offer high approval programs for:
- First-time owner-operators
- Drivers with fair credit
- Applicants leased onto carriers
4. Strategic Leverage
Financing allows you to generate revenue immediately while spreading cost over time.
Who Can Apply?
Zero down semi truck financing in Texas is available to:
- New owner-operators
- Experienced drivers transitioning from company roles
- Small fleets expanding equipment
- CDL holders leasing onto carriers
- Businesses purchasing additional units
Applicants with bad credit are not automatically disqualified. Programs exist for FICO scores as low as 550, though interest rates will vary.
Requirements and Necessary Documents
While requirements vary among top lenders, most request:
Minimum Qualifications
- Valid CDL
- 6+ months driving experience (some require 12)
- Credit score 600+ preferred (not mandatory)
- No recent repossessions or open bankruptcies
- Verifiable income or carrier contract
Required Documents
- CDL copy
- Driver record (MVR)
- 3–6 months bank statements
- Proof of residence
- Truck invoice or buyer’s order
- EIN (if operating under LLC or Corp)
Complete documentation significantly increases approval speed and may qualify you for better rates.
Best Banks and Online Lenders in Texas (2026)
Texas borrowers typically choose between traditional banks and specialized equipment lenders.
Traditional Banks
- Lower interest rates for prime borrowers
- Stricter credit requirements
- Slower underwriting
Online Lenders
- Faster may qualify for fast approval processes
- Flexible credit evaluation
- Higher approval for mid-tier borrowers
Dealership Financing
- Same day funding possible
- Convenient but potentially higher APR
When comparing lenders, evaluate:
- APR range
- Term flexibility
- Prepayment penalties
- Age restrictions on trucks
Prime borrowers seeking low interest loans may benefit from banks, while applicants with average credit often find better success through online lenders specializing in commercial trucking.
Relevant Comparisons: Zero Down vs Down Payment
| Factor | Zero Down | 10–20% Down |
|---|---|---|
| Upfront cost | $0 | $15K–$30K |
| Monthly payment | Higher | Lower |
| Total interest | Higher | Lower |
| Approval flexibility | Higher | Moderate |
| Liquidity preserved | Yes | Reduced |
For startups prioritizing liquidity, zero down often makes strategic sense. For established operators with strong reserves, a down payment may reduce total financing cost.
Interest Rates, Terms, and Payment Structures
2026 Texas Rate Ranges
- 720+ credit: 6.5%–8.5%
- 650–700: 8.5%–11%
- 600–650: 11%–16%
- 550–600: 15%–20%
Factors affecting best rates:
- Credit strength
- Revenue stability
- Truck age
- Loan term
Loan Terms
- 36–72 months standard
- Fixed-rate common
- Monthly payments typical
- Some weekly lease structures
Longer terms improve cash flow but increase total interest. Shorter terms reduce total cost but raise monthly obligation.
Best Semi Truck Models for Financing Approval
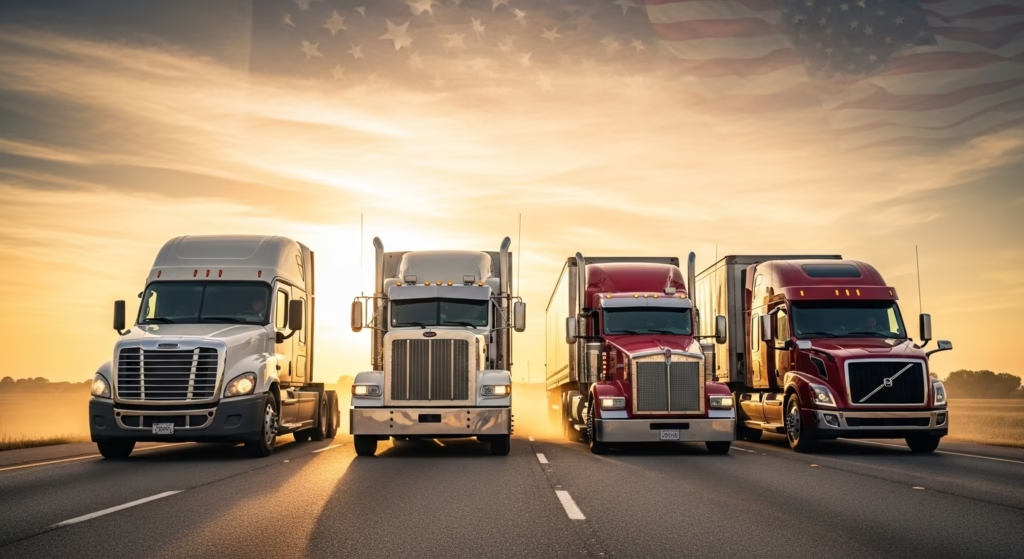
Lenders prefer trucks with strong resale value:
- Freightliner Cascadia – Fuel efficiency and strong resale
- Peterbilt 579 – Premium build quality
- Kenworth T680 – Durable and lender-friendly
- Volvo VNL 760 – Comfort + efficiency
Choosing units under 7–8 years old and below 650,000 miles improves approval odds and qualifies for lower interest brackets.
Practical Tips for Instant Approval
If your goal is same day or rapid approval, follow these tactics:
1. Strengthen Bank Statements
Maintain stable balances and avoid excessive overdrafts.
2. Reduce Credit Utilization
Lower revolving balances below 30% before applying.
3. Choose Approved Truck Age
Stay within common lender age limits.
4. Avoid Multiple Hard Inquiries
Too many applications lower approval probability.
5. Provide Complete Documentation Immediately
Delays in paperwork slow underwriting.
Applicants who prepare in advance often move from application to funding within 72 hours.
Frequently Asked Questions (FAQ)
Can I get no money down financing with bad credit?
Yes, but terms vary. Borrowers with FICO scores between 550–650 often qualify through specialized lenders. Interest rates may be higher, and additional documentation may be required. Demonstrating strong bank deposits and CDL experience significantly improves high approval chances.
Is some lenders use soft-pull pre-qualification semi truck financing real?
True some lenders use soft-pull pre-qualification programs are rare. Most lenders perform at least a soft inquiry. Some lease-to-own programs emphasize revenue verification over FICO score, but effective interest cost may be higher.
How fast can I get funded in Texas?
Pre-approval can occur within minutes. Final funding typically completes within 1–3 business days if all documentation is provided promptly.
What credit score gets the best rates?
Borrowers above 720 typically qualify for the lowest APR tiers. However, strong revenue and time in business can offset slightly lower scores.
Are online lenders safe?
Reputable online lenders specializing in commercial equipment financing are widely used in Texas. Always review contract terms, APR disclosure, and prepayment clauses before signing.
Conclusion: Compare Lenders Before You Commit
No Money Down Semi Truck Financing in Texas is a powerful entry strategy for owner-operators ready to scale without sacrificing liquidity.
However, not all zero down programs are equal.
Interest rate differences of just 2–3% can cost tens of thousands over a 60-month term. Approval standards vary widely between banks, online lenders, and dealership finance departments.
Before committing:
- Compare at least three offers
- Review APR, not just monthly payment
- Evaluate total loan cost
- Confirm truck age eligibility
- Check prepayment penalties
If you’re serious about securing the best rates with high approval odds, continue exploring lender comparisons and financing breakdowns across our site. The right structure can dramatically improve your profitability in 2026 and beyond.