An auto loan deferment may provide temporary payment relief after a financial setback, but the postponed payments, interest, and fees can increase the total cost of your vehicle. The effect on your credit depends on when the lender approves the arrangement and how the account is reported. This guide explains what to ask before signing, how to compare alternatives, and how to avoid repossession risk.
Table of Contents
What an auto loan deferment does
An auto loan deferment is a lender-approved arrangement that postpones one or more scheduled payments. It can help a borrower manage a temporary financial emergency, but it usually does not erase the amount owed. The lender may move missed installments to the end of the term, require a lump sum later, or use another contractual structure.
The key questions are whether interest continues to accrue, whether fees apply, how the due date changes, and whether the lender will report the account as current. Never assume that skipping a payment is authorized merely because a representative discussed hardship options.
Deferment versus forbearance
Lenders sometimes use the terms deferment, payment extension, skip-a-pay, and forbearance differently. A deferment commonly moves payments to a later date, while forbearance may temporarily reduce or suspend collection. The legal meaning comes from the signed agreement and applicable law rather than a marketing label.
Ask whether the agreement changes the amortization schedule, maturity date, total number of payments, interest calculation, and credit reporting. A written extension may protect your account status; an informal promise without documentation may not.
When a lender might approve it
A lender may consider hardship after job loss, reduced hours, illness, a natural disaster, or an unexpected expense. Eligibility can depend on account history, loan age, collateral value, payment status, and prior extensions. Some lenders limit the number of extensions available during the loan.
Approval is discretionary unless a contract or specific law gives you a right. Contact the servicer before the due date, describe the temporary problem, and provide a realistic plan for resuming payments. If the hardship is likely to persist, a short extension may be inadequate.
Interest usually keeps accruing
Most auto loans charge interest on the outstanding principal. Postponing a payment can allow additional interest to accrue because the balance remains unpaid longer. Even if the monthly installment is unchanged, total finance charges can rise and the payoff date may move.
The CFPB explains auto-loan interest concepts. Confirm whether your loan uses simple interest, precomputed interest, or another method. The economic effect of a deferment differs by contract.
A simple-interest example
Assume a hypothetical $18,000 principal balance and a 9% annual simple-interest rate. Approximate daily interest is $18,000 multiplied by 0.09 divided by 365, or about $4.44. A 30-day period without principal reduction could accrue approximately $133 in interest.
This is a simplified illustration, not an estimate for your statement. Actual daily balances, payment allocation, leap years, capitalization, and lender calculations can change the result. Request a written before-and-after payoff estimate rather than relying only on the monthly payment.
What happens to the deferred installment
An extension agreement may add the skipped installment to the end of the loan, lengthen the term, or require payment of accrued interest sooner. Some lenders collect an extension fee at approval. Others may require the borrower to pay interest before deferring principal.
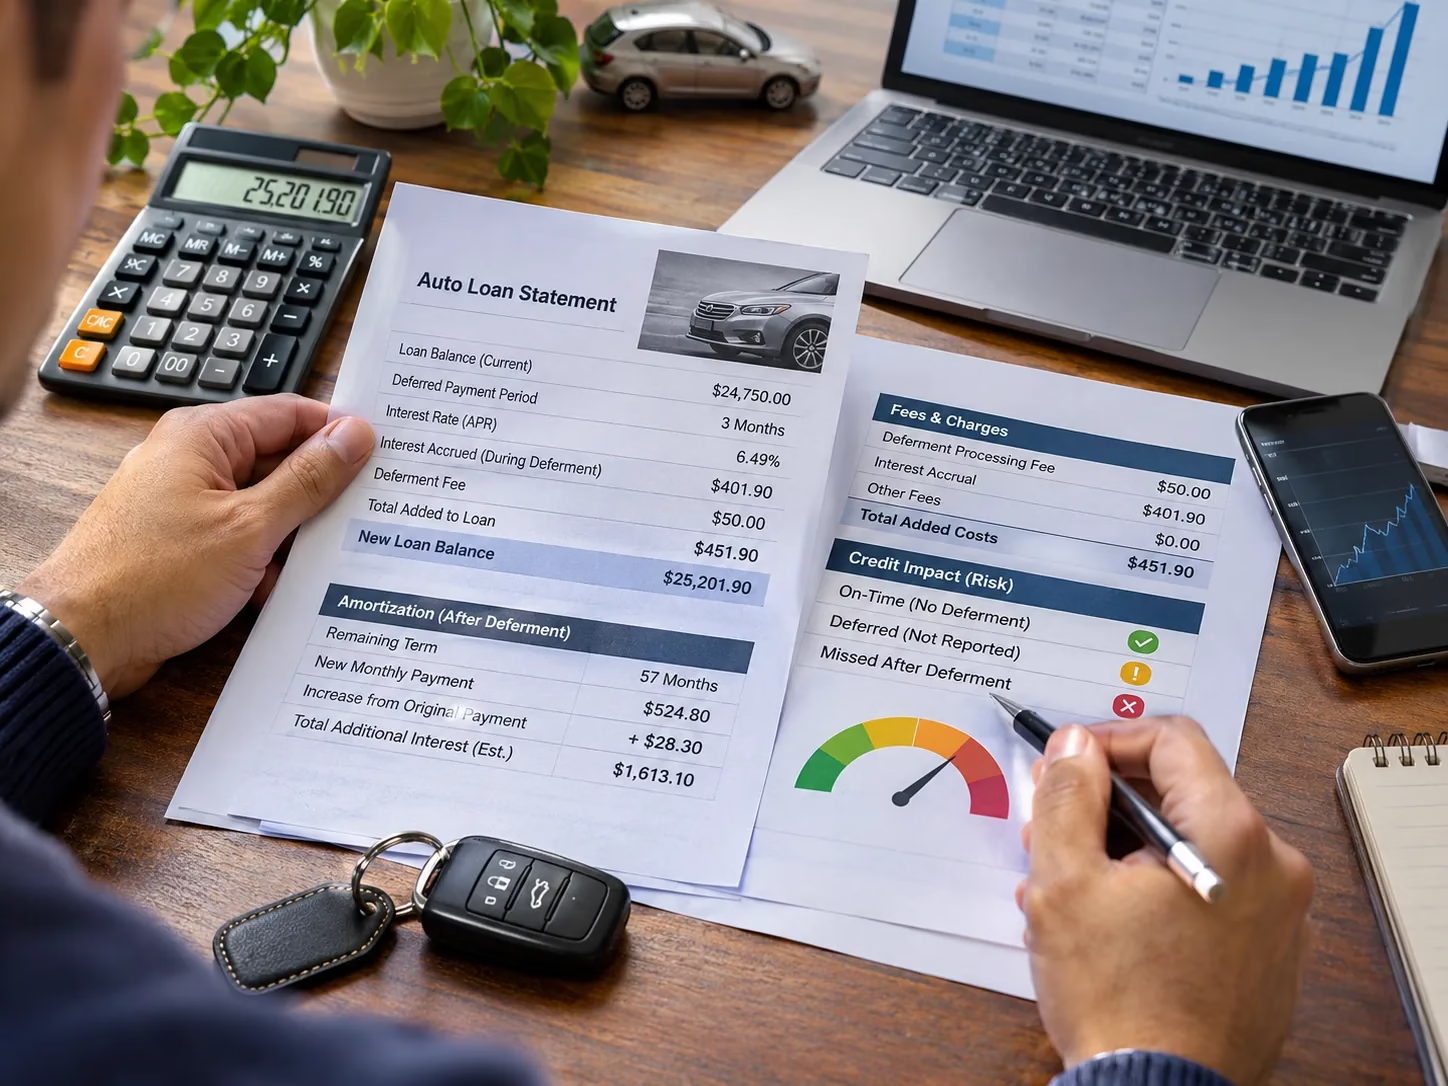
Read the exact due dates on the revised schedule. If the agreement says 'one payment deferred,' ask whether the next scheduled payment is still due in the following month. A misunderstanding can create a new delinquency immediately after a hardship arrangement.
How a deferment can affect your credit
An approved deferment that is performed according to its terms may avoid a reported delinquency, but the lender's reporting practices matter. A missed payment before approval may still be reported if it crossed the relevant reporting threshold. A deferment is not a promise that your credit score will improve.
The CFPB credit reporting resources explain how payment history affects credit. Ask how the lender will report the account, including the current status, scheduled payment, and any special comment. Verify later reports for accuracy.
Approval timing is critical
Contact the lender before the due date whenever possible. A request submitted on the due date may not be approved in time. Some servicers require signed forms, proof of hardship, or a fee before the arrangement takes effect.
Until approval is confirmed, the original contract remains the safest assumption. Record the representative's name, date, case number, and promised follow-up. Ask for a secure copy of the executed agreement and the updated payment schedule.
Late fees and extension fees
A lender may charge an extension fee, accrued interest, or a late charge depending on contract terms and state law. The same event should not automatically be treated as both a waived payment and a fee-free payment; ask which charges will actually be assessed.
The CFPB describes late fees. Request an itemized quote that separates extension fees, unpaid interest, past-due amounts, and the revised payoff balance. Challenge unexplained charges promptly in writing.
A hypothetical two-month extension
Suppose your monthly auto payment is $420 and the lender agrees to defer two payments. You may preserve $840 in immediate cash flow, but you still owe the loan balance. If interest accrues at roughly $4 per day, 60 extra days could add about $240 before balance changes and contract adjustments.
That $240 is an illustration, not a lender quote. The lender may shift maturity, collect interest separately, or structure payments differently. Compare the immediate relief with total additional interest, any fees, and the risk of another cash shortage when regular payments resume.
Does a deferment change the APR?
An extension does not necessarily change the contractual annual percentage rate. However, changing payment timing can increase total interest paid even if the nominal rate remains unchanged. Some modifications may involve new terms requiring additional disclosures.
Ask whether the APR, interest rate, payment amount, maturity date, or security interest changes. Review any new agreement carefully and seek clarification before signing. A lower monthly payment does not always mean the loan is less expensive.
Precomputed interest loans need special care
Some auto financing contracts use precomputed finance charges rather than daily simple interest. The effect of extending a payment can depend on how unearned finance charges, rebates, and extensions are treated under the contract and state law.
Do not apply a daily-interest calculator blindly to a precomputed loan. Ask the lender for its calculation method, itemized payoff amount, and the treatment of any interest rebate. Consider a consumer attorney if the disclosures are inconsistent.
Deferment versus refinancing
Refinancing replaces the existing loan with a new one, potentially changing the rate, term, payment, and total cost. A deferment usually leaves the existing loan in place but changes payment timing. Refinancing may help a long-term affordability problem, whereas a brief extension may help a short-term cash shortage.
Compare the actual offers, including origination charges, interest, loan-to-value requirements, and any longer repayment term. Our auto loan cosigner release guide discusses another reason borrowers consider refinancing.
When a lower payment creates higher total cost
Stretching a loan over more months may reduce the scheduled payment while increasing the time interest accrues. If the car depreciates faster than the principal falls, the borrower can remain upside down for longer. That can become especially costly after a total loss.
Use an amortization schedule to compare total payments and remaining principal at several future dates. Our GAP insurance refund guide explains a different issue: unused product refunds after loan payoff.
Negative equity and collateral risk
Negative equity means the loan payoff exceeds the vehicle's market value. Deferring principal reduction can prolong or worsen that gap, especially on a rapidly depreciating vehicle. This does not automatically trigger repossession, but it can limit future refinancing or sale options.
Check the lender's payoff quote and a realistic private-party or trade-in value. Avoid assuming a dealer's advertised retail price is what you could receive. If the gap is large, consider whether an extension solves the underlying affordability problem.
Insurance and protection products
Auto lenders usually require insurance on collateral. A deferment does not necessarily suspend the obligation to maintain required coverage. Missing insurance can lead to force-placed coverage, additional charges, or a contractual default.
Review your insurance declarations and loan agreement. Our force-placed insurance guide explains how expensive lender-placed coverage can arise and how to address errors.
Cosigners remain exposed
A cosigner is generally liable under the original agreement, and an extension does not necessarily release that person. Missed payments or changes in loan status can affect the cosigner's credit and legal obligations. Some modifications may require consent or notice.
Tell the cosigner about the proposed arrangement and review the contract. If a lender claims a deferment releases a cosigner, request explicit written confirmation. Never infer release from a changed payment schedule.
If you are already delinquent
A deferment may not cure all past-due amounts automatically. The lender might require a catch-up payment or offer a separate hardship modification. Credit reporting for delinquency before the agreement may remain accurate even if future installments are postponed.
Ask for a written statement of the amount needed to bring the loan current and how any existing late fees will be treated. If the servicer refuses to correct an error, preserve statements and correspondence and consider filing a CFPB complaint.
Repossession risk does not disappear
If the lender has not approved an extension, missing a payment can place the borrower in default under the contract. State law and contract terms govern repossession rights, and some states allow repossession after default without a court order.
The FTC's vehicle repossession guidance explains general risks. Our repossession deficiency balance guide covers potential debt remaining after sale of the vehicle.
A hardship request that works
State your account number through a secure channel, describe the temporary hardship, specify the payment dates you need moved, and explain when regular payments can resume. Ask the lender to list all available programs, including fee waivers, due-date changes, or temporary reduced payments.
Request the full cost in writing: additional interest, extension fees, revised maturity, next due date, and credit reporting. Do not promise a restart date you cannot meet. A credible budget can make it easier to choose an arrangement you can sustain.
Questions to ask before signing
Ask whether interest accrues during the extension, whether it is capitalized, how many payments move, and whether the loan's final payment changes. Confirm whether there are late or extension fees and whether the lender reports the account as current.
Also ask what happens to automatic payments, cosigners, insurance requirements, and the payoff quote. Save the signed documents and compare the next statement with the agreed schedule. If any term is missing, request clarification before accepting.
Alternatives to consider
Possible alternatives include changing the monthly due date, reducing discretionary expenses, negotiating other bills, selling the vehicle, or refinancing if economically sensible. Some lenders offer a short-term hardship program distinct from formal deferment.
Avoid expensive short-term borrowing merely to make a car payment without calculating the total cost. A payday loan can create a second debt problem. If you must choose among essential expenses, seek nonprofit credit counseling and review your full budget.
How to check the credit report afterward
After the extension is processed, obtain your reports and check the account status, balance, payment history, and dates. A valid extension may be reflected differently among lenders and bureaus. Focus on whether the information accurately describes the agreement.
If a lender reports a deferred installment as late contrary to its written terms, dispute the information with the furnisher and credit bureaus, enclosing the extension agreement. Our late-payment dispute guide covers similar documentation principles in mortgage reporting.
How to avoid repeated deferments
One extension may solve a temporary cash-flow gap, but repeated extensions can signal that the payment is structurally unaffordable. Review net income, essential bills, car operating costs, insurance, fuel, maintenance, and emergency savings.
Calculate how much you can reliably pay each month, not only what you can afford this week. If the loan is unsustainable, compare selling the car, replacing it with a less expensive vehicle, or restructuring debt with qualified advice.
Warning signs of scams
Be cautious of companies charging upfront fees to guarantee a lender extension or promising to erase missed payments. Only the lender or authorized servicer can approve changes to your loan. Fraudsters may impersonate servicers and demand payment through gift cards or unusual apps.
Contact the lender using the number on your statement or official website. Do not share passwords or one-time security codes with a caller. Report suspected fraud promptly and keep records of unauthorized transactions.
A pre-approval checklist
Confirm the lender's exact hardship program, application deadline, required documents, fee schedule, interest method, credit reporting policy, and next payment date. Calculate the cost of extending the loan and check whether your insurance and automatic payments remain active.
Keep the agreement, revised amortization or payment schedule, confirmation numbers, and subsequent statements. Verify that the lender actually implemented the change. If the next bill contradicts the agreement, contact the servicer before its due date.
Frequently asked questions
Does deferment hurt credit? Not automatically, but preexisting late payments and inaccurate or unfavorable reporting can matter. Does interest stop? Usually not unless the lender expressly agrees. Is approval guaranteed? No. Does a skipped payment disappear? Generally no; it is moved or otherwise addressed by agreement.
Can a lender repossess during deferment? The answer depends on the agreement and whether you remain in default. Does the cosigner leave the loan? Not merely because payments are postponed. Is refinancing better? Compare total cost and affordability rather than assuming either option wins.
Sources and editorial disclosure
Sources include CFPB auto loans resources, FTC vehicle repossession guidance, and CFPB credit reports and scores. Hypothetical calculations are illustrative; verify actual charges and payment allocation with your lender.
Meridian Pioneer Editorial Team. Our independent consumer-finance explainers rely on primary government guidance and transparent calculations. This article is educational, not personalized financial or legal advice. Loan terms and state laws vary; consult your servicer or qualified adviser about your situation.