Published October 15, 2026 · By
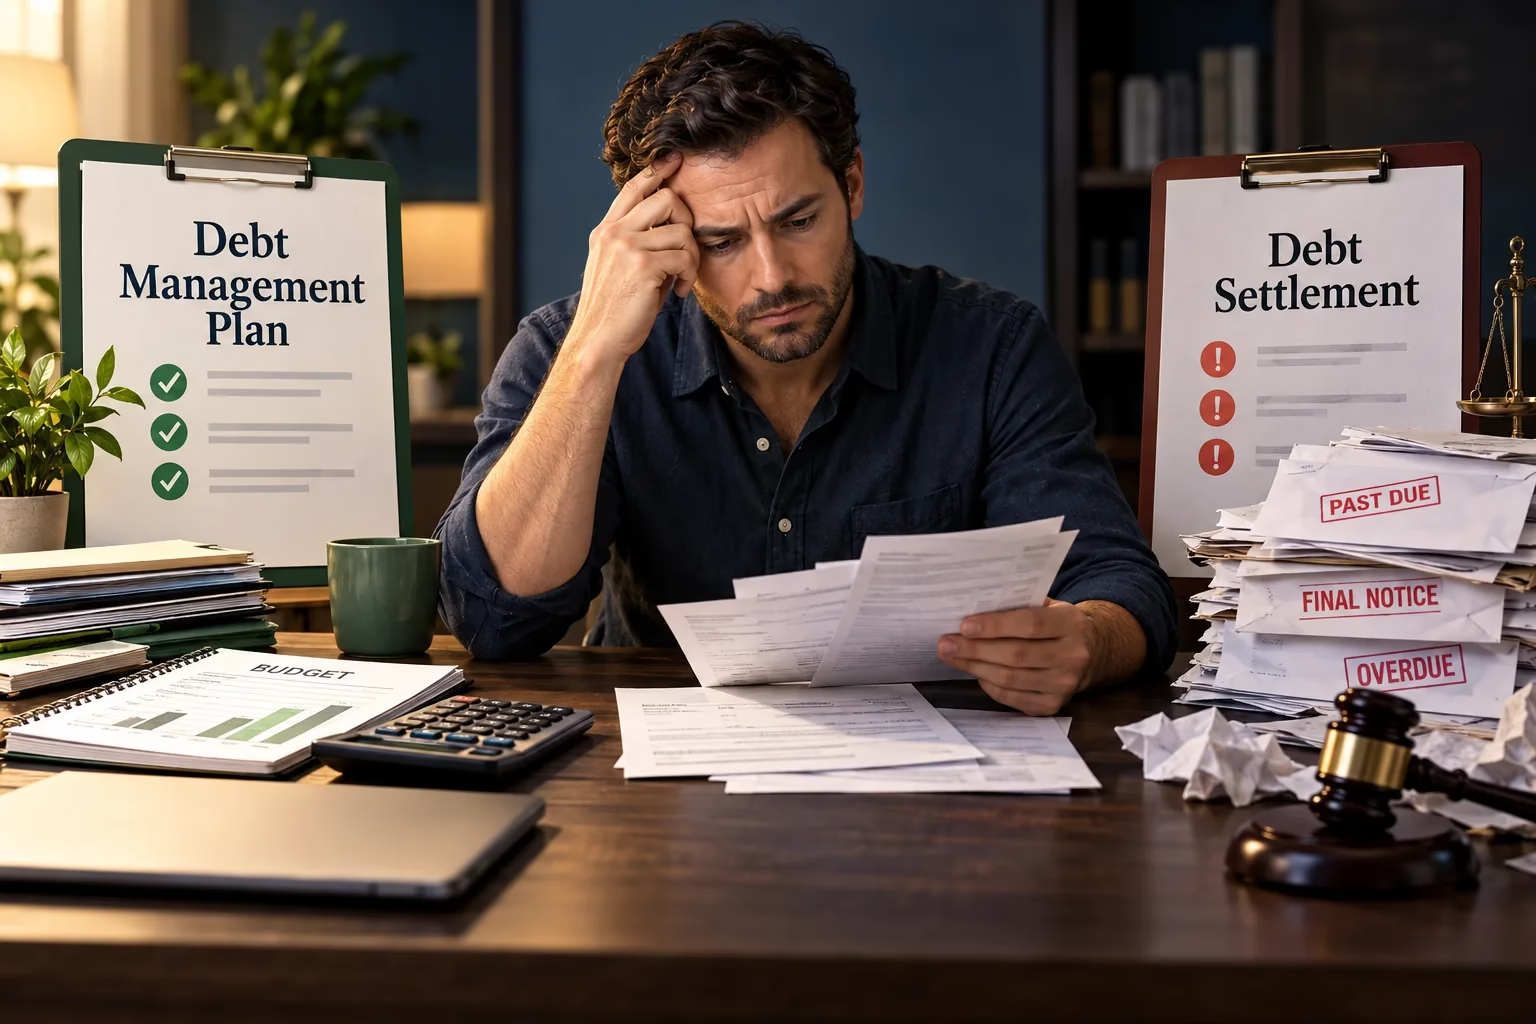
Quick answer: A debt management plan vs debt settlement comparison starts with a crucial distinction: a debt management plan (DMP) aims to repay unsecured debt, while settlement attempts to negotiate a reduction. A DMP, often arranged through a nonprofit credit counseling agency, generally aims to repay what you owe on an agreed schedule while seeking possible fee or interest concessions. Debt settlement attempts to negotiate a lower lump-sum amount accepted in satisfaction of a debt, often after a consumer has fallen behind.
A settlement strategy can involve collections, lawsuits, credit damage, accumulating interest and potential tax consequences. Neither option guarantees that creditors will agree. The Consumer Financial Protection Bureau distinguishes these approaches and recommends careful evaluation.
This guide compares debt management plans versus debt settlement from a household cash-flow perspective: how the money moves, what happens to your credit, how fees change the math, how to screen providers and what alternatives to consider. The purpose is to help consumers ask better questions, not sell a service or promise a percentage of debt relief. All numerical examples below are illustrative rather than quotes from debt relief providers.
Editorial note: Prepared October 15, 2026. Consumer protection rules and state requirements vary. This is general financial education, not individualized legal, bankruptcy or tax advice, and it has not been reviewed by a licensed attorney or certified credit counselor.
Debt management plan vs debt settlement: how the options work
A DMP is a structured repayment arrangement generally facilitated by a credit counseling organization. Rather than lending you new money, the agency reviews your budget and may help negotiate terms with participating creditors. You ordinarily make a regular payment to the organization, which distributes agreed amounts to creditors. The plan does not typically erase principal; it seeks a manageable path for paying qualifying debt in full.
The CFPB notes that counselors may arrange longer repayment periods, lower rates or reduced fees where creditors cooperate, though none of those changes is guaranteed. Before enrollment, verify that every creditor you wish to include has accepted the proposed arrangement and that the projected payment truly fits your monthly income.
A reputable counseling session should examine income, necessary living costs, assets, household priorities and unsecured balances. Credit counseling need not automatically lead to a DMP. Someone with a temporary payment problem might do better with direct creditor hardship assistance; another borrower might need independent bankruptcy advice rather than years of payments that cannot be maintained. Be cautious if the provider skips a budget review and immediately pushes its own program. The right program is a result of the assessment, not a foregone conclusion.
How debt settlement tries to reduce balances
Debt settlement involves negotiating with a lender or collector to accept an amount less than the claimed balance, often in a lump sum, as full satisfaction. A for-profit settlement company might ask a customer to build money in an account while the company attempts to negotiate deals with individual creditors. The company cannot ensure that each creditor will settle or that a particular discount will be available.
Many creditors have their own policies and may refuse to work with an intermediary. The CFPB warns that companies sometimes encourage consumers to stop making payments while saving for a settlement, which can cause additional fees, default, collection activity and lawsuits. The size of a possible negotiated reduction must be considered alongside these consequences.
Consumers should distinguish between negotiating with a creditor directly and paying a third party to negotiate. A person may be able to contact a creditor or collector themselves, explain a genuine hardship and request written settlement terms. Doing so is not inherently free of risk: creditors are not required to agree, and a settlement of an old debt may raise legal issues, such as the applicable statute of limitations. Seek qualified local advice if the debt is disputed, time-barred, in litigation or secured by important property.
7 critical facts: debt management plan vs debt settlement
| Feature | Debt management plan | Debt settlement |
|---|---|---|
| Core purpose | Repay agreed debts in an organized schedule | Seek acceptance of less than the full claimed amount |
| Creditor cooperation | Required for concessions or inclusion | Required for each negotiated settlement |
| Effect on principal | Generally repay principal rather than forgive it | May reduce balance if settlement succeeds |
| Monthly cash flow | Planned, recurring payment | Often reserve cash to attempt lump-sum settlements |
| Credit consequences | Depend on account status, program terms and reporting | Missed payments and settled balances may damage credit |
| Main failure risk | Cannot sustain agreed monthly payment | Creditor refuses, litigation occurs or savings are insufficient |
| Tax issues | Usually no debt cancellation | Forgiven debt may trigger a tax question |
No row means every plan behaves identically. Always read written creditor agreements, fee schedules and account disclosures. A DMP may lead to account closures or limitations on using revolving credit; settlement may involve legal exposure that a promotional sales script ignores. The best question is whether your situation supports a sustainable solution after realistic fees and risks are included.
Evaluate full cost instead of advertised savings
Imagine a household owes $18,000 across several unsecured credit cards. One counseling agency projects that creditors might accept a DMP with lower interest and a payment the household can sustain. A settlement advertisement claims it could negotiate a 40% balance reduction. That advertised number is not a reliable forecast.
Even if some debts eventually settle at 60 cents on the dollar, the household could accrue unpaid interest, late fees and third-party fees before each deal concludes. Other creditors might decline settlement entirely. Also, a balance written off on one account is not proof that every account has been resolved. Compare the expected total dollar outlay for each named creditor, not just a percentage in advertising.
A debt management plan vs debt settlement cost worksheet should show the opening balance of every obligation, the contractual interest rate, any overdue interest and penalties, the fee structure, projected payments, expected completion date and scenarios where creditors refuse concessions. Make a second version using conservative assumptions. If a program is affordable only because every creditor agrees immediately, it is fragile. Calculate the effect of one missed paycheck, rent increase or medical bill on the plan. The aim is a resolution you can actually finish, not the most impressive headline claim.
Understand all DMP fees before enrolling
Debt management plan vs debt settlement fees should be compared in total dollars, not just in advertised percentages. Credit counseling can be free or low-cost, but a particular DMP may have a setup fee or monthly administrative charge. Ask the provider to disclose the amount, whether it varies by state or account count, and whether any waiver is available based on hardship. Find out who receives each payment and how much is forwarded to creditors.
A counselor should explain whether the first payment occurs before all creditors formally accept the plan, and what happens to the funds if one creditor declines. Do not compare only the DMP's interest concessions while ignoring agency fees. More importantly, check whether the payment plus housing, food, utilities, transportation and necessary medical costs leaves adequate breathing room.
The Federal Trade Commission recommends selecting a counselor who reviews the entire financial situation and explains alternatives. A legitimate nonprofit label is helpful context, not proof of quality. Investigate complaints, accreditation, licensing where applicable, counselor training and written policies for complaints and refunds. Ask for a copy of the full fee schedule before sharing account numbers or signing automatic withdrawal authorization. Record every promise about interest reductions and delinquency handling in writing.
Settlement-company fees and the upfront-fee warning
Debt settlement sales can be especially confusing because a projected settlement percentage is not the same as the company's fee. Fees might be calculated as a percentage of the enrolled debt or of claimed savings, subject to applicable rules and the written agreement.
Under the federal Telemarketing Sales Rule, covered debt relief providers generally cannot charge a fee before they have successfully renegotiated a debt, the consumer has agreed to the result and the consumer has made at least one payment pursuant to the settlement. State laws can impose additional restrictions. The FTC warns that companies demanding payment before any result are a serious red flag. See the FTC debt relief guidance.
Do not confuse money you place into a dedicated settlement account with a provider's earned fees. The CFPB discusses how dedicated accounts should remain under consumer control, with restrictions on administration and withdrawal. Ask who controls the account, which institution holds it, whether it earns interest, whether you can withdraw funds without penalty, and what occurs if you cancel the service. Never grant access to a personal banking password or send settlement money to an unverified recipient because of a high-pressure phone call.
Debt management plan vs debt settlement: credit score impact
The credit impact of a debt management plan vs debt settlement is not a simple switch. In a DMP, creditors might close or restrict cards, report repayment terms or update account status according to their procedures. Existing late payments do not disappear simply because a plan begins. Timely payments on included accounts can help stop the problem from worsening, but no counselor can guarantee a point increase or a particular timeline.
In settlement, a common strategy of stopping payments may create delinquency, charge-offs and collections before any agreement is reached. A settled account may report that less than the full balance was paid. The effects depend on existing history and reporting practices, and precise score predictions are not dependable.
Check your consumer credit reports and save balances and payment histories before enrolling in either plan. Ask how the provider expects participating creditors to report accounts and whether card closure is required. Do not pay anyone who claims they can remove accurate, timely negative information just by invoking a secret dispute process. The CFPB identifies credit repair as a distinct service and warns about claims that consumers cannot verify. Your goal should be stable finances and truthful reporting, not temporary score manipulation.
Tax considerations when a creditor forgives debt
Tax treatment is another important distinction in a debt management plan vs debt settlement comparison. Forgiveness of part of a debt may create a federal income-tax issue depending on the circumstances, exclusions and tax year. A lender may issue a Form 1099-C for certain canceled amounts, but receiving or not receiving that form is not the complete legal analysis. Insolvency, bankruptcy and other exclusions or exceptions can matter, and their applicability is fact-specific.
A debt management plan generally aims to repay principal, so it does not typically create the same cancellation question. Do not accept a provider's blanket statement that settled debt is always tax-free or always taxable. Review the IRS's Topic No. 431 on canceled debt and consult a qualified tax professional for your case.
Keep settlement letters, canceled-balance statements, payment records and tax forms. If someone claims tax treatment is already included in their settlement fee, request written information about the qualifications of the person giving the advice. Debt relief programs are not substitutes for individualized tax counsel. The proper cost calculation may need to include potential tax consequences, but do not invent a precise tax liability until the facts are known.
When a debt management plan might make sense
When weighing debt management plan vs debt settlement, a DMP may be worth evaluating if debts are mostly unsecured, income is reasonably stable, the household can afford a negotiated recurring amount, and the consumer wants to repay obligations without opening another loan. It can also help someone who struggles to coordinate many payment due dates and would benefit from a structured repayment schedule. But the creditor list matters: mortgages, vehicle loans and most other secured debts generally require different solutions. The FTC says credit counselors should not treat a DMP as a one-size-fits-all remedy or recommend one without analyzing the budget first.
A useful self-test is to project the payment through the entire estimated term rather than only the first three months. Suppose your income fluctuates because of seasonal work; set aside funds during stronger months, but consider whether the required payment would still be manageable in a weak month. Ask whether the program has a procedure for temporary hardship and what happens if a payment is late. A plan that relies on optimistic assumptions may not offer durable relief.
When settlement can present especially high risks
The debt management plan vs debt settlement decision needs extra care when creditors are threatening legal action or your payments are still current. Settlement can be particularly dangerous when you remain current on your credit accounts but a marketer urges you to stop paying, when you have substantial assets exposed to creditor claims, when a lawsuit has already been filed, or when the suggested saving period is long enough for fees and interest to accumulate significantly.
It may also be a poor fit if the provider cannot explain how individual creditors participate or how it will deal with accounts that refuse negotiation. The CFPB points out that not all creditors will negotiate, and providers cannot promise the outcome of a future negotiation.
Someone with debts already in collection might still evaluate direct settlement, hardship arrangements, nonprofit counseling or legal options, but those decisions should be made with a clear picture of the legal status of each account. Do not assume that a call from a collector establishes that the requested amount is correct. Obtain validation information and preserve records. If the debt comes from a questionable medical charge, our guide to disputing an incorrect medical bill explains how to document an error before paying. Be alert to outdated debts and state-specific limitation periods; acknowledging or paying a debt can affect legal rights under some state laws.
Compare three alternatives before signing up
Before deciding between a debt management plan vs debt settlement, evaluate options that could reduce costs without intentionally missing payments. The right choice depends on your cash flow, account status and access to affordable credit.
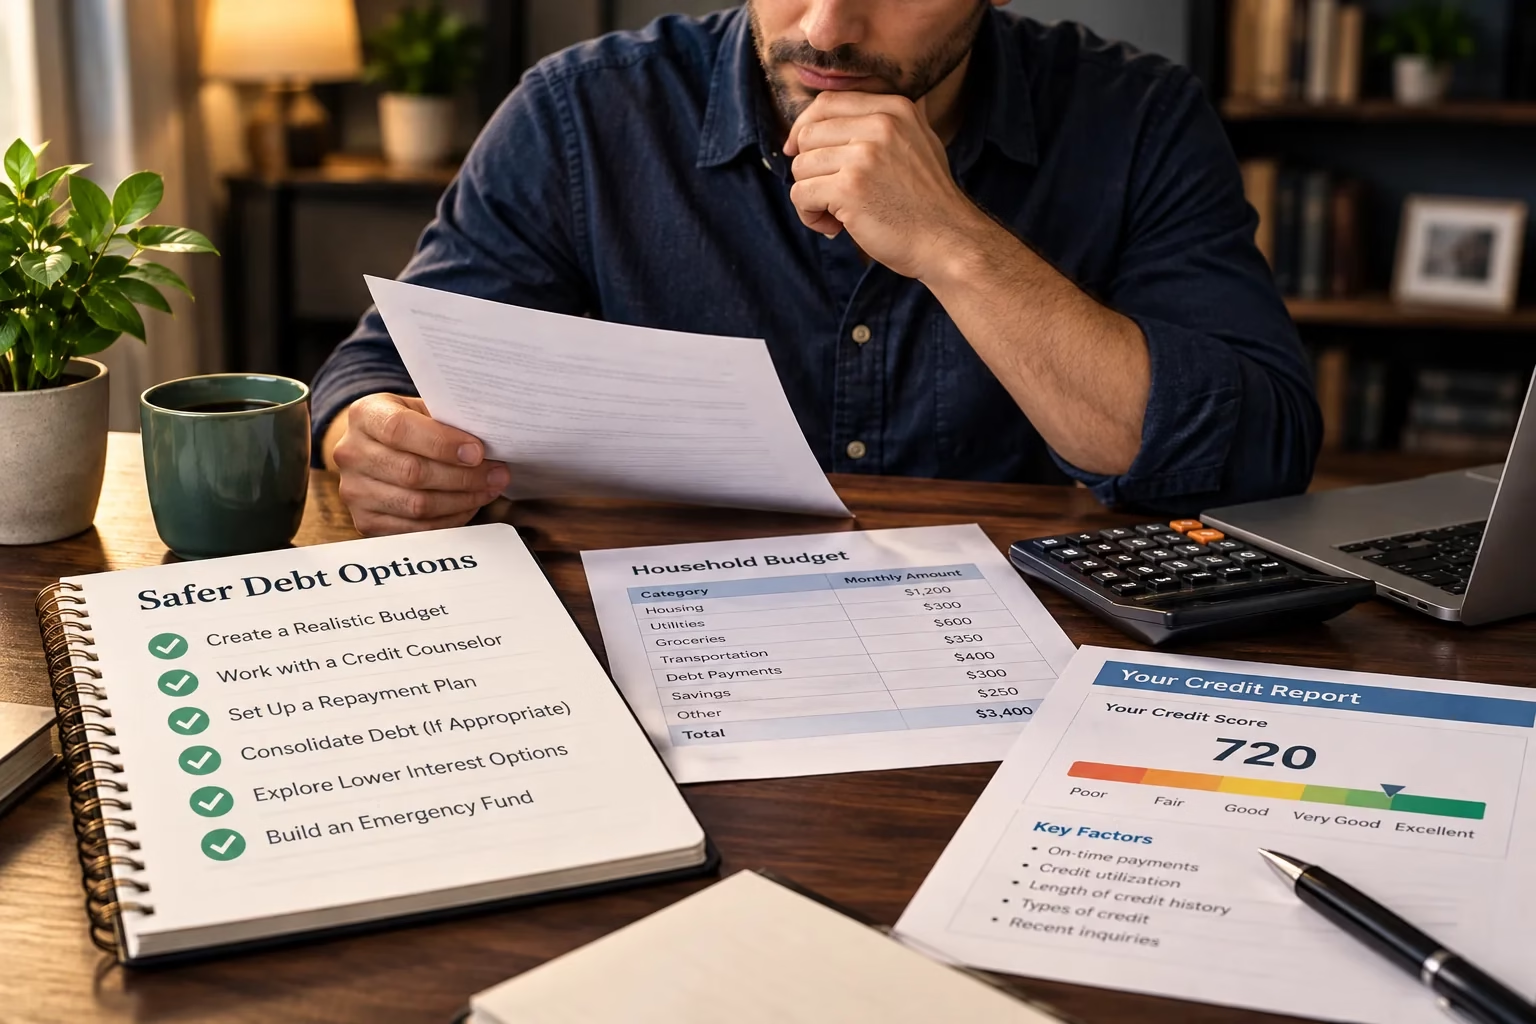
Contact creditors directly. Some issuers offer temporary hardship arrangements or payment modifications, and the terms may be more favorable than paying a third party. Explain what payment is realistic and ask for the agreement in writing. Consider a balance transfer card if eligible. A 0% introductory APR balance transfer may reduce interest temporarily, but you must consider transfer fees, the promotional deadline and the regular APR afterward. Approval is not guaranteed, and this option is not suitable when you cannot maintain the required payments. Evaluate a debt consolidation loan. One new loan can combine payments, but compare APR, origination fee, payoff term and total borrowing cost.
Extending the term can make a payment smaller while increasing the total expense. Our debt consolidation guide explains relevant trade-offs. Seek bankruptcy advice. Where obligations are fundamentally unaffordable, speaking with a qualified bankruptcy attorney may be more responsible than draining savings for a settlement plan with no workable end.
Do not assume taking out a home equity loan to pay cards is safer simply because its advertised APR is lower. Converting unsecured debt into debt secured by your residence introduces potential foreclosure risk. Evaluate the additional interest, fees, longer payoff period and effect on household resilience before pledging essential property as collateral.
How to evaluate a nonprofit credit counseling agency
Ask whether the organization is genuinely nonprofit, which credentials its counselors hold, which creditors commonly participate, how fees are determined, and whether it makes compensation arrangements clear. Review its privacy practices and find out whether you can receive counseling without buying a repayment service. Contact creditors independently to confirm any proposed rate concession or fee waiver. Check consumer complaints through appropriate regulators and confirm whether licenses are required in your state. A credible agency should explain both the benefits and the limitations of a DMP and will not guarantee a particular credit score.
Request a written budget review and an individualized plan before allowing account withdrawals. Understand how payments will be allocated if one creditor refuses the arrangement or closes an account. Ask what data is shared with creditors and how your payment history can be checked. If a counselor pressures you to make an immediate decision without reading the terms, comparison shopping is warranted. The CFPB credit-counseling guidance explains the services a counselor can provide.
Questions to ask a debt settlement company
Ask for the fee formula in dollars, not only as a percentage. How much debt must be enrolled? Who decides when to propose a settlement? Which creditors have declined to negotiate in comparable circumstances? What happens if a lawsuit arrives? How will the company handle tax forms? When may fees legally be earned?
Where is your dedicated settlement savings held, and what are the withdrawal rights? What happens to untouched debts if you leave the program? Which state-specific registrations and consumer protections apply? If the representative cannot answer these questions plainly and in writing, you do not have enough information to consent.
Ask whether the provider guarantees or implies a certain savings percentage. A guarantee should be treated with skepticism because individual creditors control their own acceptance decisions. Check that a proposed agreement really satisfies the full balance with the correct account owner, not merely postpones collection. Never send money to a debt collector or settlement company without verifying its identity using contact information independent of an unsolicited message.
Build a realistic household debt inventory
A reliable debt management plan vs debt settlement comparison begins with a complete debt inventory and a budget built around essential expenses, not a provider's advertised monthly payment.
List each creditor, account balance, annual interest rate, minimum payment, due date, delinquency status, collateral and whether any legal action is pending. Separate debts secured by a home or vehicle from unsecured obligations such as ordinary credit cards. Then list take-home income, housing, utilities, food, transport, health needs and a modest reserve for irregular costs.
What remains is the maximum amount available for a sustainable repayment arrangement—not the amount a salesperson says you should save. Compare your budget with each provider's written payment plan and stress-test what happens if one month of income is lower than expected.
Keep a dated folder containing creditor statements, any collection validation notices, written fee quotes and your notes from calls. Update it whenever a balance changes. A useful debt plan is measurable: the household should be able to see which obligations are being resolved, which fees are owed and whether the strategy still works. If the numbers cannot be explained after a short review, pause rather than enrolling out of anxiety.
How to avoid common debt relief scams
Some advertisers use debt management plan vs debt settlement terminology interchangeably. Confirm in writing whether the provider proposes repaying balances in full under a plan or trying to negotiate partial repayment with individual creditors.
Be suspicious of unsolicited messages that promise immediate elimination of every debt, demand sensitive details before explaining services or insist on large upfront payments. The FTC warned in 2026 that people seeking debt relief can be targeted by dishonest firms that take money while leaving them worse off. Legitimate counselors can describe services, fees, alternatives and risks without pressuring you to sign on the same call. Verify the provider's legal name and contact details independently, review regulator complaint databases, and never pay a fee merely to receive a promised guaranteed outcome.
If something goes wrong, preserve advertisements, payment receipts, recordings you lawfully possess and copies of contracts. Consider contacting the FTC at ReportFraud.ftc.gov, the CFPB or relevant state authorities. Avoid sending personal account numbers or Social Security numbers in public reviews. A complaint may help document a problem but does not itself guarantee reimbursement.
What to do during the first 30 days
Days 1–7: Collect balances, confirm account status, stop adding new optional debt where possible and prepare a realistic budget. Speak with a lender about hardship programs before simply ceasing payments. Days 8–14: Contact at least one nonprofit counseling service and ask for an independent review, not just a plan enrollment. Explore consolidation only after evaluating APR and fees. Days 15–21: Compare written plans, creditor acceptance, cancellation rights and any potential tax or legal consequences. Days 22–30: Choose an affordable path, preserve documents and set monthly review checkpoints.
This timeline is an organizational example, not a legal deadline. A pending lawsuit, foreclosure notice or expiring statute may require immediate qualified legal help. If credit accounts are already in distress, a workable solution usually begins with accurate information and direct communication, not an assumption that a discount advertised online will apply to your debts.
Frequently asked questions about DMPs and settlement
Will a debt management plan erase debt?
Usually not. A DMP generally aims to repay balances under a coordinated arrangement. Concessions may involve interest or fees rather than forgiveness of principal.
Does settlement always lower my total cost?
No. Even where a creditor accepts less principal, late fees, additional interest, provider fees and possible tax consequences can offset some savings. Other creditors may refuse entirely.
Can I handle a settlement myself?
You can communicate directly with creditors and request written terms, but unresolved legal issues, expired limitations periods or lawsuits deserve professional review. Do not agree to a disputed debt without understanding your position.
Is a nonprofit counseling agency automatically safe?
No organization is automatically trustworthy. Verify its services, fee schedule, state obligations, complaint record and whether proposed creditor arrangements exist.
Can a debt settlement company guarantee that every creditor participates?
No. Creditors may decline negotiations and policies differ. A promised universal success rate should prompt skepticism.
Bottom line: choose the plan you can finish
The debt management plan vs debt settlement decision is ultimately about affordability, creditor cooperation and legal exposure—not a guaranteed savings percentage.
A debt management plan may offer structure and potential interest concessions while preserving the goal of repaying what you owe. Debt settlement seeks negotiated reductions but can expose consumers to delinquency, legal action and uncertain fees. Both require a realistic budget and written documentation. If the situation is already beyond affordable repayment, consult a qualified bankruptcy attorney rather than enrolling in a program that depends on implausible monthly contributions. Start by contacting creditors, obtaining a nonprofit counseling evaluation and comparing the total cost—not a marketing headline.
Primary references
- CFPB: Credit counseling, debt settlement and consolidation
- FTC: How to get out of debt
- FTC: Debt relief scam alert (2026)
- CFPB: Credit counseling
For our editorial standards, see the Meridian Pioneer editorial policy.