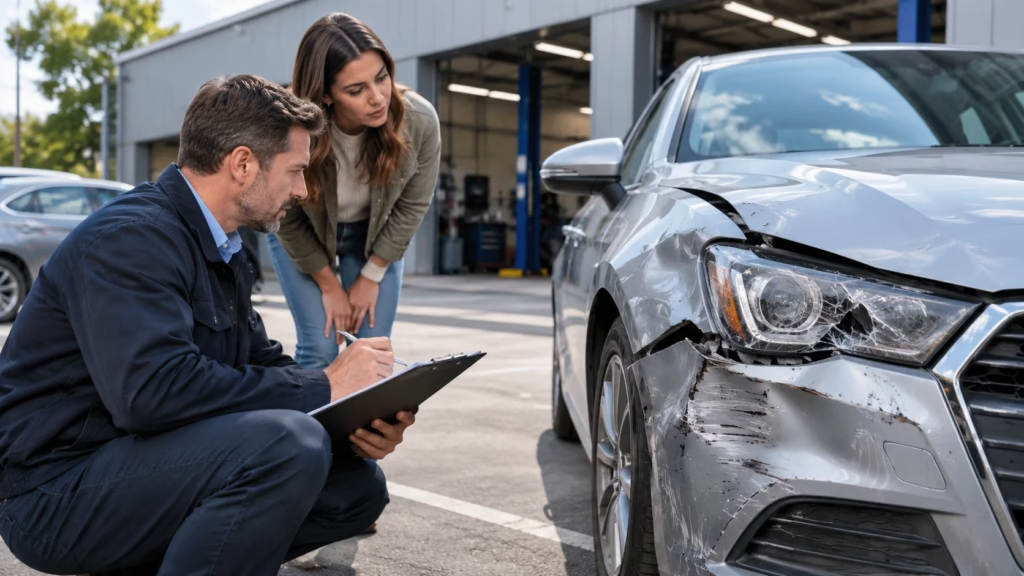
A diminished value claim after an accident seeks compensation when a repaired vehicle is worth less because of its collision history. The amount and availability depend on state law, fault, insurance coverage, repair quality, and actual market evidence. This guide explains how to document loss, challenge a low offer, and avoid treating any formula as a nationwide rule.
Table of Contents
What diminished value means
Diminished value is the reduction in a vehicle's market value after a collision and repair. A properly repaired vehicle may still sell for less because buyers see an accident history, worry about hidden damage, or discount the vehicle's future reliability. That difference can be economically real even when the repair shop restores normal appearance and function.
Insurance treatment depends on who caused the crash, which coverage applies, and state law. A diminished value claim is not automatically available under every policy or in every jurisdiction. Distinguish the actual market loss from a generic percentage quoted by a website.
Three types of diminished value
Inherent diminished value refers to market stigma after proper repairs. Repair-related diminished value describes a residual loss attributable to poor or incomplete repair work. Immediate diminished value is the difference in market value directly after the crash, before repair. Claimants most often discuss inherent diminished value after repairs are finished.
These categories help organize evidence but are not universal legal definitions or separate guaranteed benefits. Insurers and courts may evaluate the loss using different terminology. Describe the condition of your specific vehicle, repair quality, and comparable sales rather than relying only on a label.
Third-party claims versus your own policy
A third-party property damage claim is made against the at-fault driver's liability insurer. A first-party claim is made under your own collision or other applicable coverage. Some states treat diminished value differently in these contexts, and first-party policies may expressly exclude market-value loss after repairs.
The Georgia Office of Insurance and Safety Fire Commissioner provides consumer auto insurance information, but rules are not uniform across states. Review the actual policy, the accident's location, fault allocation, and applicable case law with a qualified professional.
Georgia's distinctive legal history
Georgia is often discussed because its Supreme Court addressed first-party diminished value under a particular automobile policy in State Farm Mutual Automobile Insurance Co. v. Mabry, 274 Ga. 498 (2001). The case does not mean every insurer nationwide must pay diminished value or that every Georgia driver receives a fixed percentage.
Georgia insurance practices and policy language still require case-specific analysis. The frequently discussed '17c' formula arose from litigation and insurer practices; it is not a universal federal rule or a guaranteed measure of a particular car's actual market loss.
Why state law controls
Insurance is principally regulated at the state level. The availability of a diminished value claim can depend on tort law, contract interpretation, fault rules, limitation periods, policy exclusions, and state insurance guidance. A driver in one state should not rely on a settlement example from another.
The National Association of Insurance Commissioners provides an overview of auto coverage. State insurance departments and state courts supply the controlling details. If your case involves an out-of-state crash or policy, ask which jurisdiction's law governs.
Fault and comparative negligence
For a third-party claim, the other driver's liability matters. If you share responsibility for the collision, comparative-fault rules may reduce or bar recovery depending on state law. Police reports can be evidence but do not necessarily settle legal fault.
Preserve photographs, witness contacts, traffic-camera records where lawfully available, and the insurer's liability determination. Ask for a written explanation of any fault percentage used to reduce the offer. If fault is contested, consider consulting an attorney before accepting a full release.
When diminished value may be small
Older vehicles, high mileage, prior accidents, preexisting damage, and limited local demand can reduce the measurable difference between pre-loss and post-repair value. Conversely, a newer vehicle with a clean history and significant structural repairs may show a larger market discount.
Neither age nor repair cost creates an automatic legal cutoff across all states. A $10,000 repair bill does not prove a $10,000 diminished value claim. The central question is the vehicle's actual market value with and without the accident history, supported by credible evidence.
What accident history reports show
Vehicle-history reports may list collisions, damage severity, salvage events, or other records, but they can be incomplete or inaccurate. A buyer may still discount a vehicle based on disclosed repairs even when the report lacks an entry.
Obtain the available vehicle-history report and check its accuracy. Keep repair invoices, photographs, structural measurement sheets, and post-repair inspection records. If the report contains an error, dispute it with the reporting company rather than assuming the insurer must compensate for incorrect data.
Repair completion before valuation
A post-repair inherent diminished value assessment is generally more reliable after the repair shop completes the work and the car can be inspected. Outstanding safety or cosmetic defects may require supplemental repairs rather than only a diminished value payment.
Request the final itemized repair invoice, supplement approvals, calibration records for driver-assistance systems, and warranty details. Inspect the vehicle carefully. Document unresolved problems immediately, because a release signed too early may complicate additional repair or value claims.
Collecting comparable vehicle prices
Start with vehicles of the same year, make, model, trim, drivetrain, approximate mileage, equipment, and condition. Look for local dealer listings and documented transactions when available. Separate clean-history comparables from vehicles with similar accident records.
Listings are asking prices, not necessarily sale prices. Adjust for mileage, geographic market, dealer fees, condition, and options. A comparison based on one unusually expensive listing is weak; multiple well-matched examples create a more credible range.
Professional appraisal versus online estimates
An independent appraiser can inspect repairs, analyze market comparables, and explain a reasoned loss estimate. Some insurers accept appraisals as useful evidence, but they are not bound to agree. Online calculators can provide a rough starting point but may not reflect local transaction data.
Before paying an appraiser, ask about credentials, methodology, inspection scope, written report, and total fee. Determine whether the expected potential recovery justifies the expense. No appraisal can guarantee the insurer or court will accept its conclusion.
A hypothetical diminished value calculation
Suppose a car with no accident history would reasonably sell for $28,000. Comparable repaired cars with documented similar collisions sell for $25,500 after adjusting for mileage and equipment. The estimated inherent diminished value is $2,500. This is a market-comparison illustration, not a standard formula.
If the insurer offers $900, the gap is $1,600. The driver should ask what market data supports the offer and provide contrary evidence. A disagreement over the estimate is not proof of bad faith; the relevant evidence and governing law determine the outcome.
Understanding the 17c formula
Some claims discussions use a '17c' calculation that starts with a base loss cap and applies damage and mileage modifiers. The resulting number can differ substantially from a well-supported market appraisal. Its legal relevance and insurer use vary by jurisdiction.
Do not accept or reject a settlement solely because it matches or differs from 17c. Ask the adjuster to disclose the actual calculation, damage classifications, mileage assumptions, and supporting data. Compare the result with market evidence rather than a nationwide percentage myth.
Building a strong claim packet
Prepare a concise demand letter with the accident date, claim number, vehicle identification, liability basis, final repair documentation, accident history, market comparables, appraisal if obtained, and requested amount. Explain why the car's market value remains lower despite repairs.
Keep the packet factual and easy to verify. Use a numbered exhibit list and reference specific documents rather than sending an unsorted folder of photographs. Preserve copies and note when the insurer receives the submission.
A practical demand letter structure
Begin by identifying the vehicle and collision. State whether the claim is third-party or first-party and the basis for liability or coverage. Describe the completed repairs and the remaining market stigma. Then explain the valuation methodology and amount requested.
Close by asking for a written response and a copy of the insurer's contrary valuation if it disagrees. Avoid threats or exaggerated claims. A professional presentation can make the dispute easier to evaluate, but does not replace proof of loss or establish legal entitlement.
How adjusters evaluate the request
The insurer may review liability, policy terms, repair invoices, age and mileage, prior damage, comparable sales, appraisals, and any previous payments. Some adjusters use internal models; others request an inspection or specialist review.
Ask whether the insurer has accepted coverage or liability and which issue remains disputed: eligibility, amount, documentation, or prior settlement. Separate these questions. A detailed written response helps you decide whether to supplement evidence, negotiate, or pursue a formal complaint.
Negotiating a low settlement offer
Request the insurer's valuation report and ask for the specific comparable vehicles and adjustments. Correct factual errors in trim, mileage, prior damage, and repair severity. Submit additional relevant local sales evidence rather than repeating the same demand without support.
Consider the cost of further appraisal, time, and potential litigation. A smaller but well-supported recovery may be more practical than an expensive dispute over an uncertain amount. Do not sign a release until you understand whether it settles all property damage, including supplemental repairs and diminished value.
State insurance department complaints
If the insurer fails to explain its decision or appears to violate claim-handling rules, a state insurance department may accept a consumer complaint. Regulators can review compliance but typically cannot decide every disputed market-value fact or act as your private attorney.
Use the NAIC state insurance department directory to locate the proper agency. Include the claim number, policy details, correspondence, and concise explanation. Keep separate track of any court filing deadline.
Small claims and civil court
Depending on the amount and jurisdiction, small claims court may offer a way to pursue a disputed third-party property damage claim. Filing limits, service rules, evidence requirements, and statutes of limitation vary. Some disputes must proceed through arbitration or another contractual process.
Check local court guidance before filing. Obtain written appraisals and admissible evidence, and confirm the correct defendant. A state insurance complaint generally does not extend a lawsuit deadline. For significant losses, consider consulting an attorney.
Leased and financed vehicles
A loan balance is not the same as market value. You may owe more than a repaired car is worth, but that does not automatically prove diminished value. Leases can create additional questions about who owns the vehicle and who has the legal right to recover loss of value.
Review your lease or financing agreement and ask the lessor or lender about claim proceeds. Our GAP insurance refund guide concerns a different product: refunds after early loan payoff, not compensation for accident-related market stigma.
Total loss is a different valuation dispute
If an insurer declares a vehicle a total loss, the dispute generally concerns actual cash value and settlement deductions rather than post-repair inherent diminished value. Do not combine the two calculations without checking state rules and the claim's actual status.
Our total-loss settlement guide explains comparable vehicles, valuation adjustments, taxes, and fees. For a repaired car, focus on the market discount remaining after competent repair.
Prior accidents and overlapping claims
A car with previous collision history may already have suffered a market discount. A new claim should measure additional loss attributable to the new crash, not count the same historical damage twice. Prior repairs can also make comparable selection more difficult.
Disclose known preexisting damage accurately. Preserve earlier repair records if available and ask an appraiser to separate old and new effects. Misrepresenting accident history can undermine the entire claim and may raise insurance fraud concerns.
Deadlines and release language
The deadline to bring a claim may depend on state statutes of limitation, contract terms, claim type, and the date of loss. Insurer correspondence does not necessarily stop the legal clock. A release may waive further recovery for specified property-damage losses.
Ask for the release in advance and read the scope carefully. Confirm whether rental expenses, supplemental repairs, towing, or diminished value are included. Our loss-of-use coverage guide addresses another potential accident-related expense.
Mistakes that weaken claims
Common mistakes include relying on a generic percentage, ignoring prior accidents, using mismatched comparables, submitting only repair bills, exaggerating damage, failing to document completed repairs, and accepting a full settlement before understanding the release.
A strong submission explains the difference between pre-crash and repaired market values with transparent adjustments. Be prepared for a reasonable range rather than insisting on one precise figure without supporting evidence.
Questions to ask before accepting an offer
Ask which state's law applies, whether the claim is first-party or third-party, whether liability is accepted, what valuation method was used, which comparables were considered, and whether the offer includes a full release. Ask for a written breakdown of any prior payments.
Also ask whether unresolved repair issues can be addressed separately and whether appraisal or dispute-resolution provisions apply. Keep the response and the final signed documents with your insurance records.
Frequently asked questions
Can you claim diminished value after a repaired accident? Potentially, depending on fault, coverage, and state law. Does the insurer have to pay 10% of the car's value? No nationwide rule guarantees that amount. Is a repair invoice enough? Usually not by itself.
Can you claim against your own insurer? It depends on policy language and state law. Does a clean repair eliminate all market loss? Not necessarily. Is 17c legally required everywhere? No. Should you hire an appraiser? Compare the likely benefit with the fee.
Sources and editorial methodology
Consult the NAIC auto insurance consumer guide, state insurance regulator directory, and Georgia insurance resources. For legal interpretation, read the controlling state statute, policy, and court decisions. Hypothetical calculations are illustrative, not guaranteed settlement amounts.
Meridian Pioneer Editorial Team. We develop independent consumer-finance explainers using primary regulatory guidance and clearly labeled examples. This educational content is not personalized legal or insurance advice. Consult a licensed insurance professional or attorney in the relevant jurisdiction for individual claims.